Roof Damage Documentation for Philadelphia Insurance Claims
A roof claim goes better with clear evidence: dated photos, a written list of damage tied to the storm, and a repair estimate that includes what the city's code requires. That is the part a roofer can do, and we do it thoroughly.
For a roof insurance claim in Philadelphia, we inspect the roof, photograph and document the storm damage, write a repair estimate, and meet your adjuster on the roof to point out what we found. Under Pennsylvania law only a licensed public adjuster or an attorney can negotiate your claim or interpret your policy, so we stay on the construction side.
What a Roofer Can and Cannot Do on a Claim
Your insurer sends an adjuster to decide what the policy covers. Our job is to make sure the damage is found and recorded properly, and that the repair estimate reflects what the work actually requires. Good documentation is what most disputed claims are missing.
What we do not do is negotiate your settlement, tell you what your policy covers, or promise that insurance will pay for a roof. In Pennsylvania that is licensed public adjuster work. If you want someone to negotiate for you, hire a licensed public adjuster or an attorney.
What Affects the Cost of Claim Documentation
- Size of the roofMore slopes and edges take longer to document.
- AccessSteep, tall or slate roofs need more setup.
- Adjuster visitsTime on site with the adjuster.
- SupplementsUpdated estimates when new damage is found.
- Repair scopeThe repair itself is priced in the written estimate.
There is no published local range for claim documentation, and we will not quote what an insurer might pay. The repair estimate itself is based on the work the roof needs.
Damage Documentation and Photo Report
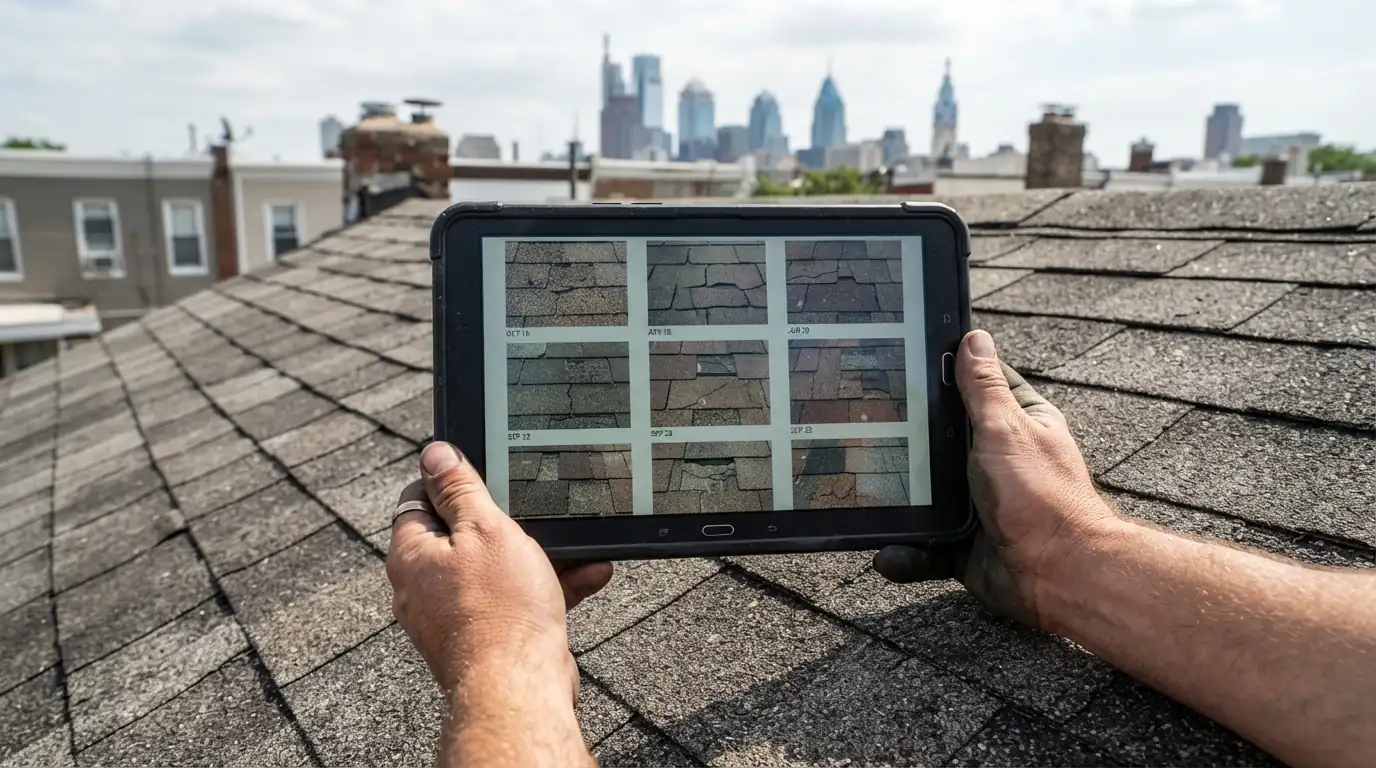
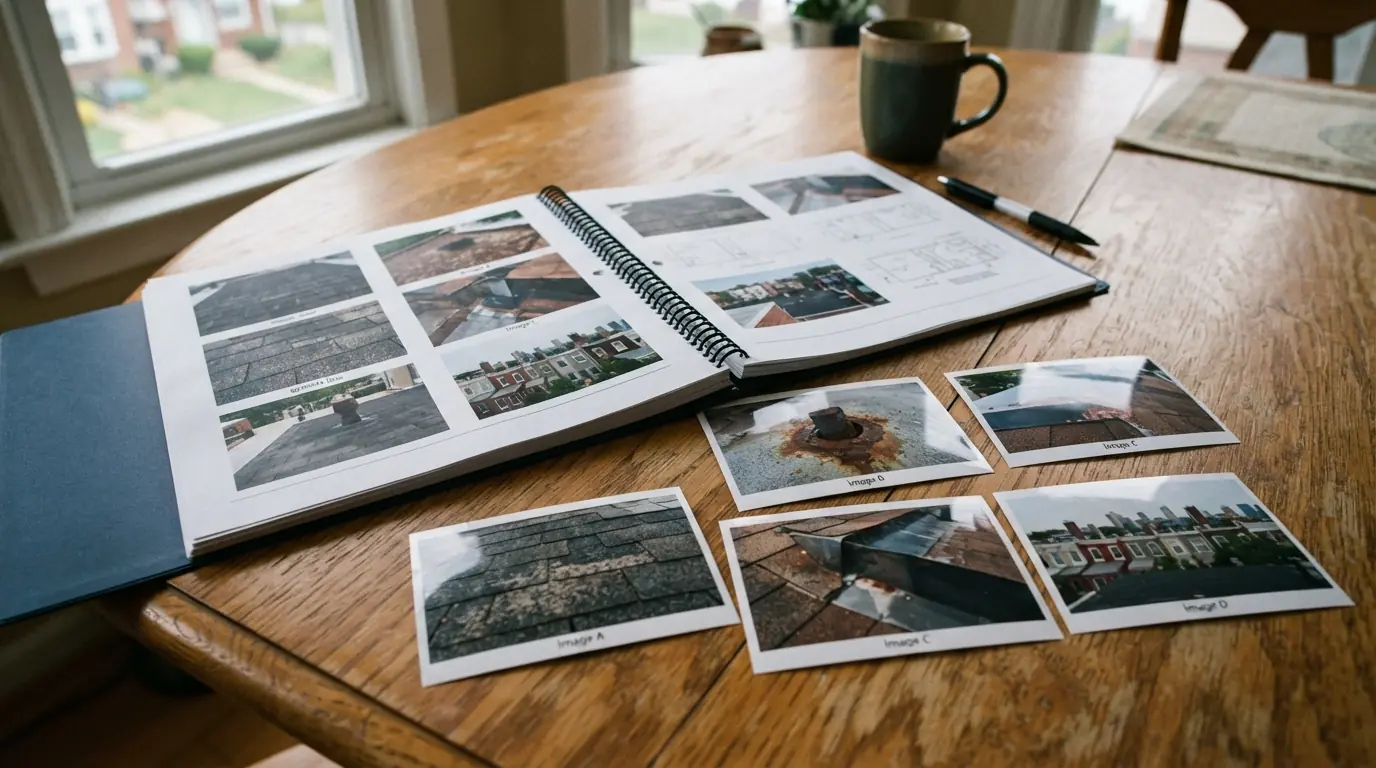
After a storm we inspect every slope, edge, vent and gutter, not just the spot that leaked. Damage is marked, measured and photographed with dates, alongside wider shots that show where on the roof each photo was taken. The written report lists what we found by location on the roof and ties it to the storm date. It separates storm damage from ordinary wear, because an honest report is more credible to an adjuster than one that calls everything storm damage.
Adjuster Meeting on the Roof
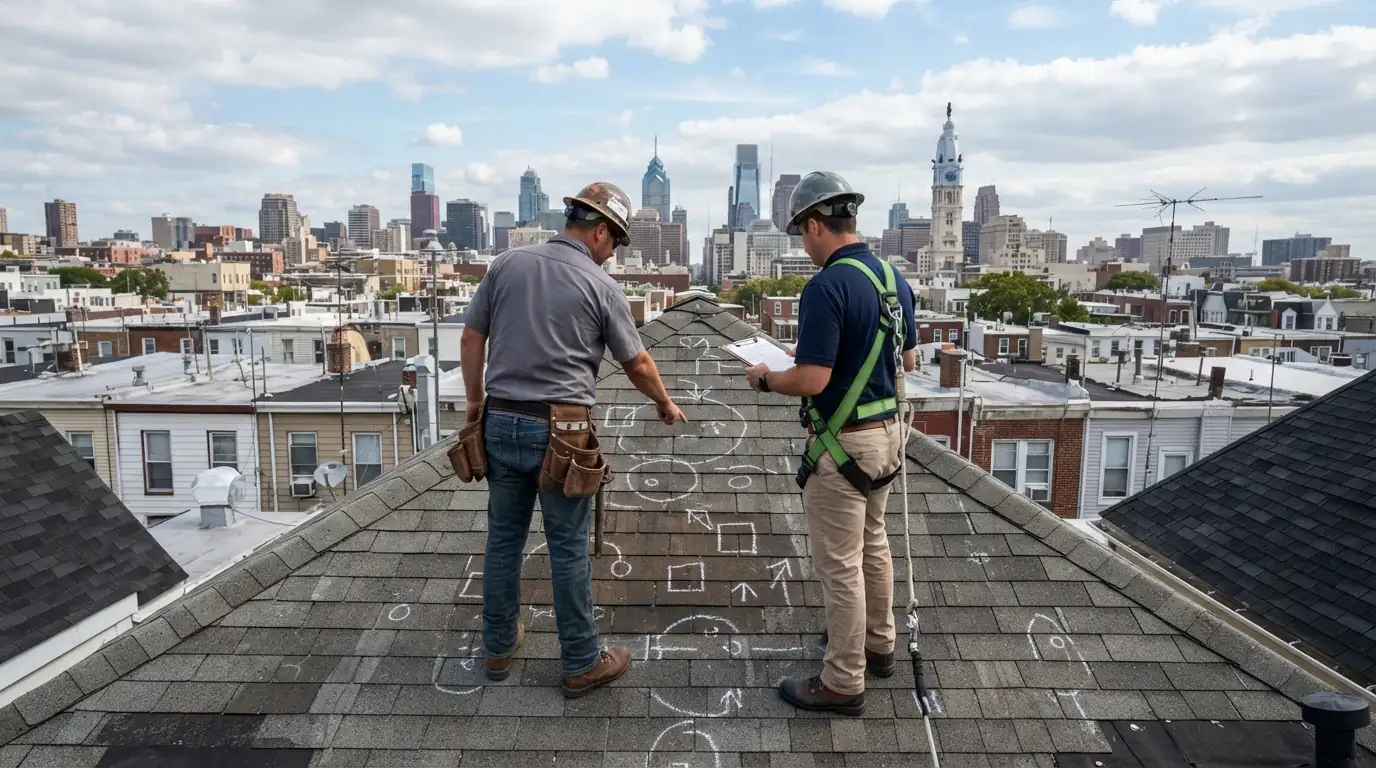
When your insurer schedules an inspection, we can be there. We walk the roof with the adjuster, point out the damage we documented, and answer questions about how the roof is built and what the repair requires. We do not argue coverage or settlement amounts; that is between you and your insurer. Being present simply means that real damage is not missed because the adjuster had a short visit or could not safely reach a steep or high part of the roof.
Supplement and Scope Review
Sometimes damage only shows once the old roofing is off: soft decking, a hidden layer, or flashing that has to be replaced to do the job. When that happens we document it with photos and send an updated repair estimate, so the insurer sees what was found and why the work changed. Code-required items belong in the estimate too, such as a full tear-off where two layers are already on the roof. Coverage decisions stay with you and your insurer.
What to Gather Before You File
Most of this is in your hands already. We supply the roof side of it.
- Date and time of the storm
- Your own photos from the ground and inside
- Our dated roof photos and damage report
- Our written repair estimate
- Receipts for any emergency tarping
- Your policy number and declarations page
- Notes on every call with your insurer
- Adjuster's name and inspection date
- Copies of anything you sign
Storm damage and a claim to file?
Call and we document the roof before you talk to your insurer.
What We See on Philadelphia Roofs
Pennsylvania's public adjuster law draws a clear line: a roofer can inspect, document, estimate and meet the adjuster, but only a licensed public adjuster or an attorney can negotiate a claim, and a contractor acting as an adjuster needs separate contracts and cannot start work until the claim is decided. On Philadelphia roofs the estimate also has to reflect the city's rule that a roof carrying two layers must come off to the deck.
How We Help With a Roof Claim
- 1
Protect the roof
Emergency tarping first if water is getting in.
- 2
Full inspection
Every slope, edge, vent and gutter checked.
- 3
Photo report
Dated photos and a written damage list.
- 4
Repair estimate
Scope and price for the work, including code items.
- 5
Adjuster meeting
We show the adjuster what we documented.
- 6
Repair after approval
Work scheduled once you decide how to proceed.
Roof Insurance Claim Questions
No. In Pennsylvania only a licensed public adjuster or an attorney can negotiate your claim. We document and estimate.
That depends on your policy and the damage. Your insurer decides; we will not promise an outcome.
Protect the house first, then have the roof documented so you know what you are reporting.
Only emergency protection. Permanent repairs usually wait so the adjuster can see the damage.
Share our photo report with your insurer, and consider a licensed public adjuster if you want representation.
More Storm & Emergency Work in Philadelphia
From our guides: After a Storm: Your Roof and Your Insurance Claim
Start the Claim With Good Evidence
Call after a storm. We document the roof honestly and give you an estimate you can share with your insurer.